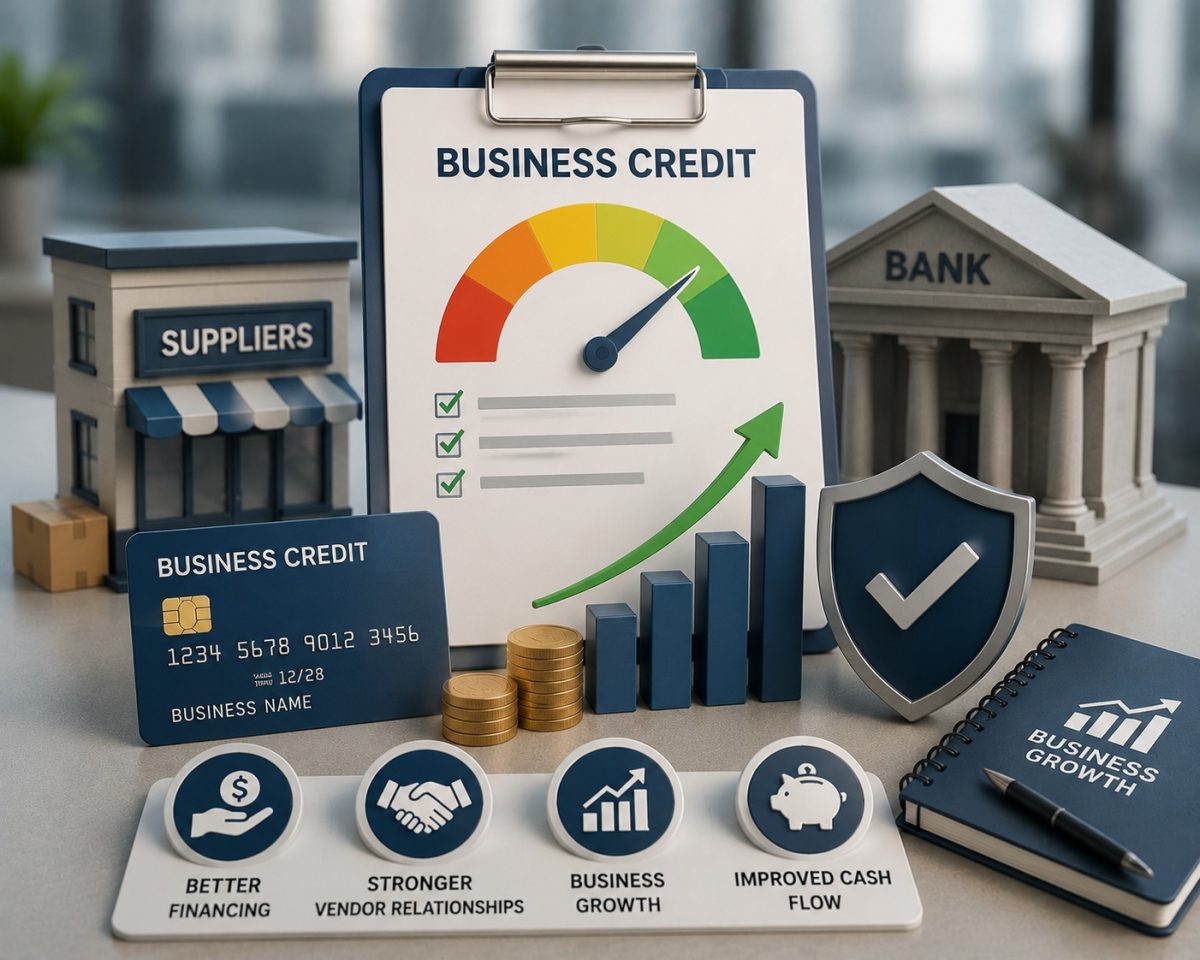
Strong business credit is usually built through consistent financial behavior rather than shortcuts. A company needs accurate business information, accounts established in its proper name, dependable payment habits, controlled borrowing, and enough time for creditors and commercial reporting systems to develop a useful history.
Separate the Business Financially
Keeping company finances organized makes the business easier to evaluate. Use the legal business name consistently, maintain appropriate registrations, obtain required tax identification, and operate through dedicated business banking rather than mixing routine personal and company spending.
The SBA notes that incorporated entities can establish credit separately from their owners, while sole proprietorships generally do not have the same legal separation. Its business credit overview describes establishing accounts in the company’s name as part of building a business credit profile.
Legal separation does not mean a lender will ignore personal credit. New businesses are sometimes evaluated using the owner’s financial history, particularly when a personal guarantee is requested.
Establish Accounts That Create a Payment Record
A credit profile becomes useful when there is real payment activity behind it. Vendors, lenders, card issuers, and other creditors may report business accounts, although reporting practices differ.
While reading online business strategy material, avoid assuming that opening many accounts automatically creates strong credit. An account is only helpful if it fits the company, is managed responsibly, and is actually considered by future creditors.
Ask potential vendors or financial providers how their reporting works before opening an account solely for credit-building purposes.
Pay Reliably and Keep Borrowing Manageable
Payment history is one of the clearest signals a business can control. Build systems that prevent missed invoices, unnoticed automatic charges, or payments being delayed because the owner is waiting for customers to pay.
Owners comparing revenue management discussions should also watch liquidity. A company can have growing sales and still experience payment trouble when customer receivables arrive after bills are due.
| Credit-Building Action | Purpose | Potential Problem |
|---|---|---|
| Separate business accounts | Cleaner financial record | Requires consistent bookkeeping |
| Pay obligations on time | Builds payment history | Cash shortages can disrupt payments |
| Monitor credit files | Detect incorrect information | Reports can differ |
| Limit unnecessary debt | Protects repayment capacity | Excess applications add obligations |
Borrow because the financing serves the business, not because more accounts appear impressive.
Review Reports and Correct Genuine Errors
Business information can change as companies move, reorganize, change names, or open additional locations. Periodically checking commercial credit information can help owners identify outdated or incorrect records.
Some entrepreneurs encounter general wealth-building material promising faster financial results. Be cautious of any service claiming it can manufacture a legitimate credit profile instantly or remove accurate information simply because it is inconvenient.
The FTC continues to warn consumers about credit-repair schemes involving false promises, illegal upfront fees, or instructions to misrepresent information.
Shortcuts Can Create Bigger Problems
Buying unnecessary tradelines, repeatedly applying for financing, or paying expensive services solely to chase a particular score can cost more than it helps.
Another mistake is assuming business credit eliminates personal liability. Loan and card agreements may still require personal guarantees, especially for newer companies. Always read the contract instead of relying on assumptions about how the account “should” work.
Credit strength develops from real commercial activity. Artificial-looking transactions are a poor substitute for ordinary invoices paid as agreed.
When Should a Business Get Professional Advice?
Talk with a qualified accountant, attorney, lender, or financial professional if you are unsure how business structure affects liability, whether a personal guarantee is appropriate, or how a financing agreement could affect company assets.
Professional help may also be useful when a significant reporting error cannot be resolved through the reporting agency’s normal dispute process or when the company is already struggling with debt.
Frequently Asked Questions
How quickly can a new business establish credit?
There is no guaranteed timeline. Development depends on the company’s structure, accounts, reporting activity, payment history, borrowing behavior, and the scoring system a creditor uses.
Does an EIN automatically create strong business credit?
No. An EIN identifies a business for federal tax purposes but does not by itself establish a strong payment history or guarantee financing approval.
Can business credit replace personal credit completely?
Not always. Established companies may qualify based heavily on business finances, but lenders can still request personal guarantees or review owner information depending on the product and business history.
Build Credit Through Ordinary Good Management
The fastest sustainable route is often less exciting than advertised shortcuts: keep company finances separate, use credit only when it serves a real purpose, pay obligations reliably, and monitor records for errors. Strong business credit should emerge from sound financial operations rather than become a separate project that encourages unnecessary borrowing.
This article provides general financial information and is not individualized credit, lending, tax, legal, or investment advice.